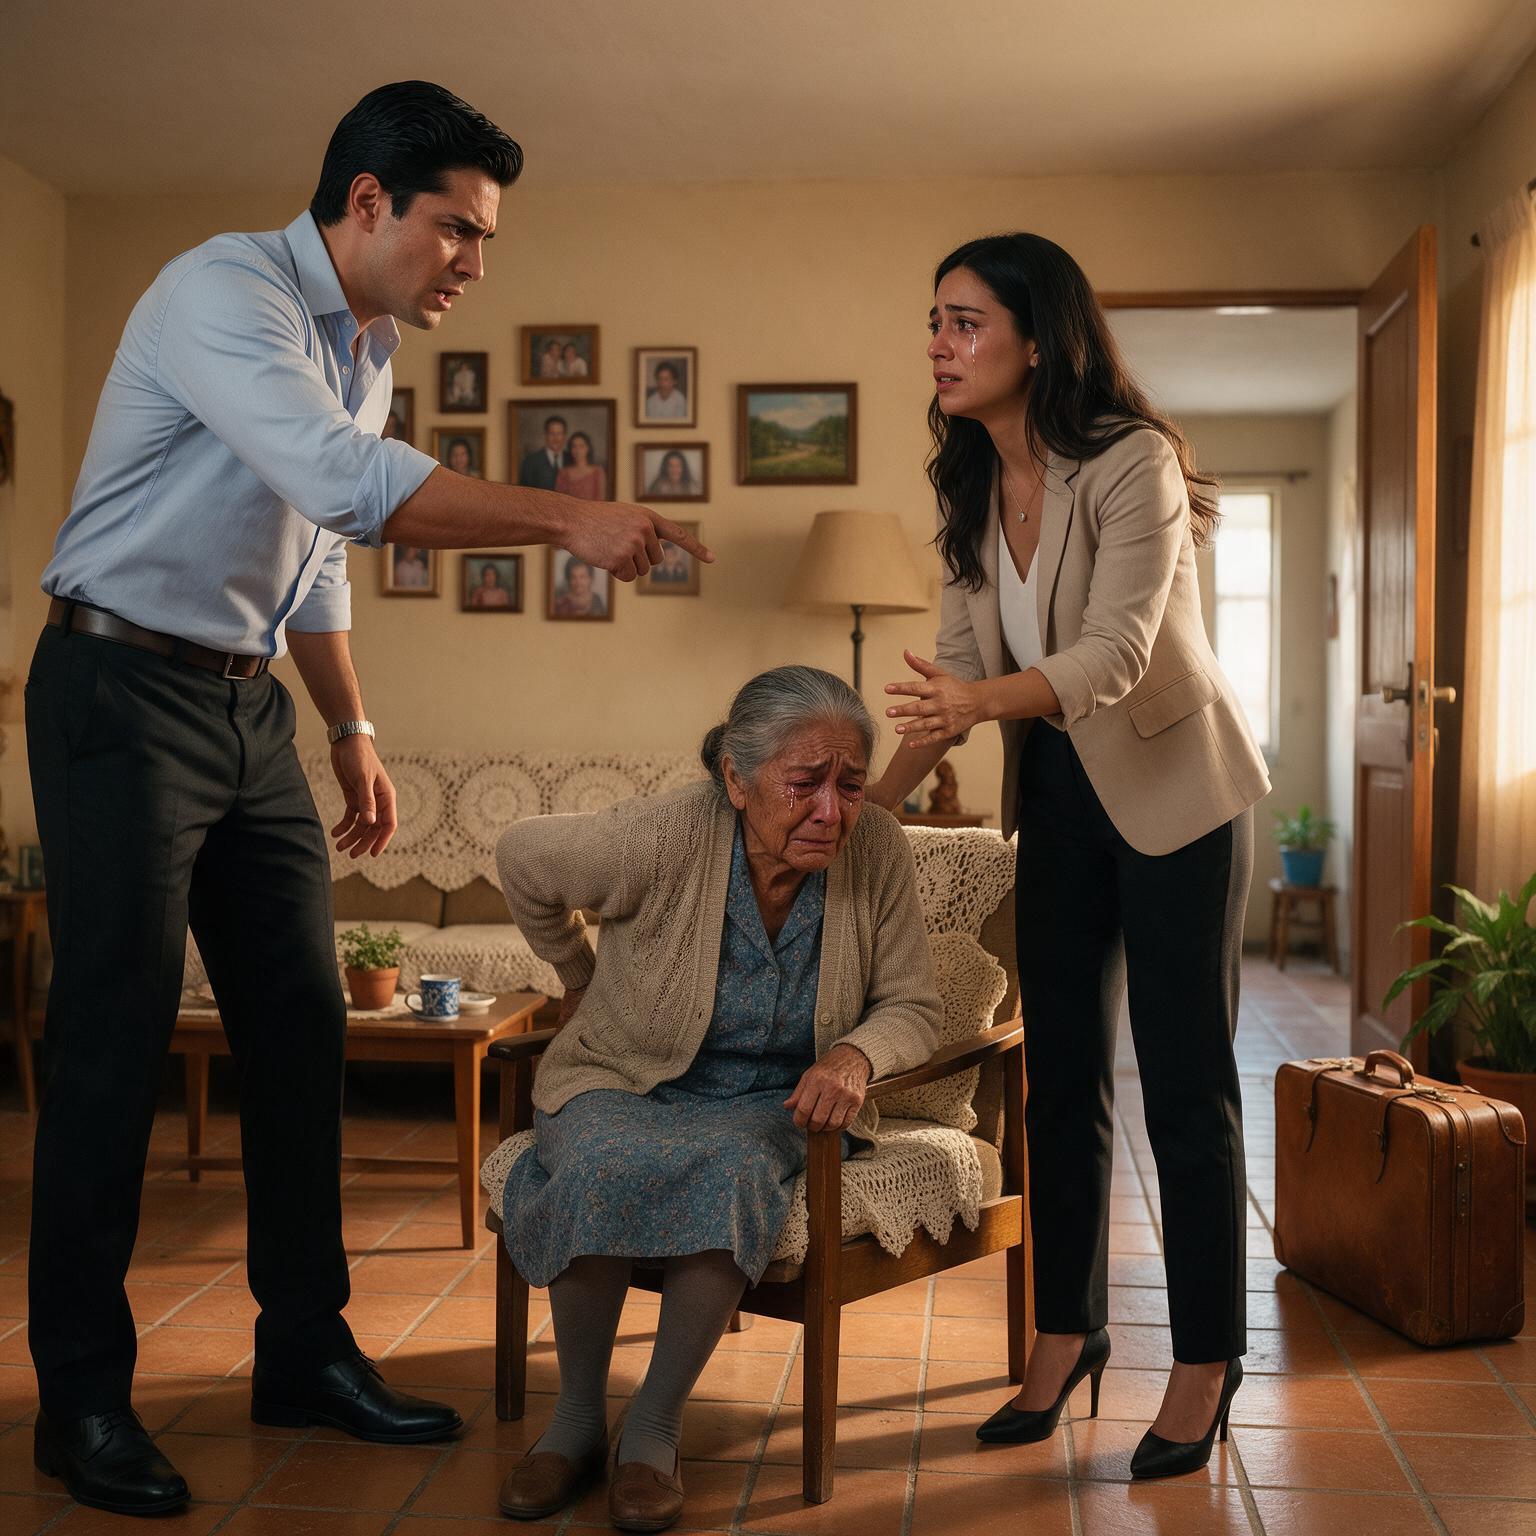Congress’ 396–13 Housing Vote That Could Reshape America
A vote of 396 to 13 is difficult to ignore in a deeply divided Washington. On May 20, 2026, the U.S. House of Representatives delivered exactly that kind of overwhelming result, advancing a sweeping housing package designed to confront one of the most persistent economic problems facing American families: the rising cost and shrinking availability of housing. The vote was not merely another procedural moment on Capitol Hill. It represented an unusually broad bipartisan acknowledgment that the nation's housing shortage had become serious enough to demand federal action, even from lawmakers who rarely agree on major domestic policy. The measure at the center of the vote was the 21st Century ROAD to Housing Act, H.R. 6644, a broad legislative package aimed at expanding housing supply, reducing regulatory barriers, reforming financing, supporting manufactured and rural housing, and addressing the growing influence of large institutional investors in the single-family housing market.
The numbers themselves tell an extraordinary political story. According to the official House roll call, 396 representatives voted in favor and only 13 voted against the May measure, while 21 members did not vote. Support crossed party lines on a scale rarely seen in contemporary congressional politics. All 204 Democrats who cast votes supported the measure, along with 191 Republicans and one independent member. The 13 opposing votes came from Republicans. Because the measure was considered under suspension of the rules, it required a two-thirds majority of those present and voting. It cleared that threshold comfortably.
Behind that striking vote was a problem affecting Americans far beyond Washington. Housing affordability has become a defining economic concern as families confront high home prices, elevated borrowing costs, limited inventory and rents that consume increasingly large shares of household income. The fundamental challenge is not simply that homes cost more. In many parts of the country, there are not enough homes in the places where people want and need to live. Building new housing can be slowed by permitting requirements, local land-use restrictions, financing challenges, infrastructure limitations and construction costs. The ROAD to Housing Act attempts to attack that problem from several directions rather than relying on a single federal program.
The House package contained dozens of provisions addressing housing supply, mortgage financing, manufactured housing, rural communities, veterans and community banking. The National Low Income Housing Coalition described the House version as a broad bipartisan package containing 56 housing-related provisions. This breadth helps explain why the legislation attracted lawmakers with very different political philosophies. Conservatives could support regulatory and banking reforms intended to make construction and lending easier, while Democrats could point toward affordable housing, rural programs and restrictions on large corporate investors. The result was a legislative coalition built not around agreement on every housing issue, but around a shared conclusion that the existing system was failing too many Americans.
One of the most politically visible elements concerned institutional investors in the single-family housing market. Large investment firms have increasingly become a symbol of the affordability crisis, particularly in communities where prospective homeowners find themselves competing against companies capable of purchasing houses at scale. The debate is complicated because institutional investment can also finance rental housing and new construction. The House and Senate therefore disagreed over how aggressively federal policy should restrict these investors.
The May House version sought to limit acquisitions by large institutional owners while avoiding rules lawmakers feared could discourage the construction of new rental homes. This became one of the central differences between the House and Senate versions. Reporting at the time noted that the House had softened portions of the Senate approach, particularly rules affecting build-to-rent companies. That disagreement meant the enormous 396–13 vote was not the end of the legislative process. Senators Tim Scott, a Republican, and Elizabeth Warren, a Democrat, both indicated that additional work would be required before the Senate could accept the House version.
That detail is important because a viral video showing the 396–13 result can easily create the impression that Congress had completed the entire process in a single dramatic vote. It had not. The May vote was a major milestone, but the Constitution requires the House and Senate to agree on identical legislative text before a measure can proceed toward becoming law. The two chambers continued negotiating after the May vote.
The housing package also focused heavily on increasing supply. Rather than treating affordability exclusively as a subsidy problem, lawmakers increasingly approached it as a production problem. If demand for housing exceeds the number of available homes, prices and rents face persistent upward pressure. Building more units therefore became a central objective of the legislation.
Among the reforms discussed during the legislative process were measures intended to streamline certain federal reviews, encourage more housing-friendly land-use policies and reduce barriers affecting new construction. The legislation also placed significant attention on manufactured housing. Factory-built homes can often be produced faster and at lower cost than conventional site-built houses, making them potentially valuable in markets where traditional construction has become prohibitively expensive. The House legislation included changes intended to modernize rules governing manufactured housing and make this form of construction more practical.
Financing was another major component. Increasing the number of homes means little if ordinary buyers cannot obtain affordable mortgages. Community banks and smaller lenders can play an especially important role in rural communities and markets underserved by large financial institutions. The House version therefore incorporated banking provisions designed to reduce certain regulatory obstacles and help community banks participate more effectively in housing finance. The Independent Community Bankers of America highlighted provisions involving custodial and reciprocal deposits as important components of the House package.
The legislation also addressed a less visible problem: small-dollar mortgages. Traditional mortgage economics can make relatively inexpensive homes surprisingly difficult to finance because lenders face many of the same administrative costs whether a mortgage is worth $100,000 or $500,000. When the loan is small, those fixed costs represent a larger share of potential revenue, reducing lenders' incentive to offer such products. Congressional housing reforms sought to improve access to financing for buyers who may be purchasing lower-cost homes, particularly younger and first-time homeowners.
These provisions matter because the American affordability crisis is not uniform. Housing challenges in San Francisco or New York look very different from those in a rural county, a former industrial city or a rapidly expanding Sun Belt suburb. Some regions need substantially more multifamily construction. Others have aging housing stock. Rural communities may struggle with financing and infrastructure. First-time buyers may have adequate income but face mortgage-access problems. Veterans and low-income renters confront yet another set of barriers. A broad housing bill therefore attempts to create multiple policy pathways rather than impose one national solution on every local market.
The overwhelming House vote also carried significant political meaning. Housing affordability cuts across traditional partisan divisions because Republicans, Democrats and independents all have constituents struggling to buy or rent homes. A young Republican family trying to purchase its first home faces many of the same mortgage and inventory pressures as a young Democratic family living several streets away. The political explanations may differ, but the monthly payment does not care about party registration.
That shared economic pressure created an unusual opening for bipartisan legislation. Representative French Hill of Arkansas, the Republican chairman of the House Financial Services Committee, and Representative Maxine Waters of California, the committee's ranking Democrat, were central House figures in the process. In the Senate, Banking Committee Chairman Tim Scott and ranking Democrat Elizabeth Warren became another unlikely bipartisan partnership around housing reform. The ideological distance between these lawmakers makes the legislation's progress particularly noteworthy.
Yet the 396–13 vote was only one chapter. After the House acted in May, negotiations continued. The Senate later considered another compromise and, on June 22, approved a revised housing package with overwhelming bipartisan support. The compromise included restrictions on large institutional investors acquiring additional single-family homes, alongside reforms intended to accelerate permitting, improve financing and expand housing supply. The House then concurred with the Senate amendment on June 23. Official legislative history confirms that sequence: initial House passage in February, Senate amendment in March, House action on May 20, further Senate consideration in June and final House concurrence on June 23.
The story then took an unusual constitutional turn. President Donald Trump did not immediately sign the measure. Despite earlier White House support for housing legislation, Trump withheld his signature while pressing Congress over separate election legislation concerning voter identification and proof of citizenship. Because the housing bill was neither signed nor vetoed while Congress remained in session, the constitutional process allowed it eventually to become law without a presidential signature. The official federal record lists the 21st Century ROAD to Housing Act as Public Law 119-101, approved on July 11, 2026.
That final development makes the original 396–13 vote even more interesting in retrospect. What began as an overwhelming House vote in May ultimately became one of the most significant bipartisan housing policy efforts of 2026. The enacted law's official purpose is straightforward but ambitious: “to increase the supply of housing in America, and for other purposes.”
Still, no federal statute can magically make housing inexpensive overnight. Construction takes time. Local zoning remains enormously important. Interest rates influence mortgage payments. Labor, land and material costs affect what developers can profitably build. Restrictions on institutional investors may improve opportunities for individual purchasers in some markets, but institutional ownership represents only one piece of a much larger national affordability puzzle. Federal incentives can encourage cities to change regulations, but Washington cannot simply manufacture millions of appropriately located homes with the stroke of a pen.
The real test of the ROAD to Housing Act will therefore come through implementation. Regulators will have to translate statutory language into workable rules. State and local governments will decide how to respond to incentives. Banks and mortgage lenders will determine whether financing reforms make previously uneconomic loans practical. Developers will assess whether permitting changes actually reduce time and cost. Institutional investors will adapt their acquisition strategies to the new restrictions. And families will ultimately judge the law not by the size of its congressional majority, but by whether finding and financing a home becomes meaningfully easier.
That is why the 396–13 vote matters, but not simply because the number looks dramatic on a breaking-news graphic. It represented a rare moment when lawmakers across the political spectrum agreed that America's housing system required substantial reform. The vote did not instantly lower rents or home prices, nor did it immediately make the proposal law. Instead, it pushed a complicated legislative process forward, forcing the House and Senate to negotiate differences and eventually produce a final bipartisan package.
In an era when congressional coverage often revolves around conflict, the ROAD to Housing Act tells a different political story. Republicans and Democrats disagreed over important details, particularly the treatment of institutional investors and banking regulations, but they continued negotiating rather than abandoning the effort. The legislation moved through multiple versions, survived disagreements between the chambers and ultimately became federal law.
For Americans watching from outside Washington, the significance is less procedural and more personal. Housing determines where families can live, whether young adults can leave their parents' homes, how much income remains after rent or mortgage payments, whether workers can move near better jobs and whether communities can accommodate future generations. When housing supply fails to keep pace with demand, the consequences spread through almost every part of the economy.
The 396–13 vote was therefore not merely an impressive congressional statistic. It was an early signal of something increasingly rare in American politics: overwhelming bipartisan recognition of a shared national problem. Whether the 21st Century ROAD to Housing Act ultimately delivers the affordability improvements its supporters envision will take years to evaluate. But the legislative journey from that remarkable House vote to Public Law 119-101 demonstrates that housing had become urgent enough to push Washington across its familiar partisan boundaries. In a Congress accustomed to razor-thin margins, 396 to 13 was not a whisper. It was a political alarm bell about the cost of having a place to call home.
ÁLVARO OBLIGÓ A SU MADRE ANCIANA A LIMPIAR EL SUELO DE RODILLAS… PERO CUANDO CLAUDIA DIJO «LA CASA ESTÁ A SU NOMBRE», EL MALETÍN QUE ÉL ESCONDÍA REVELÓ UNA TRAICIÓN IMPERDONABLE
PARTE 1: LA VERDADERA DUEÑA DE LA CASA
—¡De rodillas! Así no queda limpio.
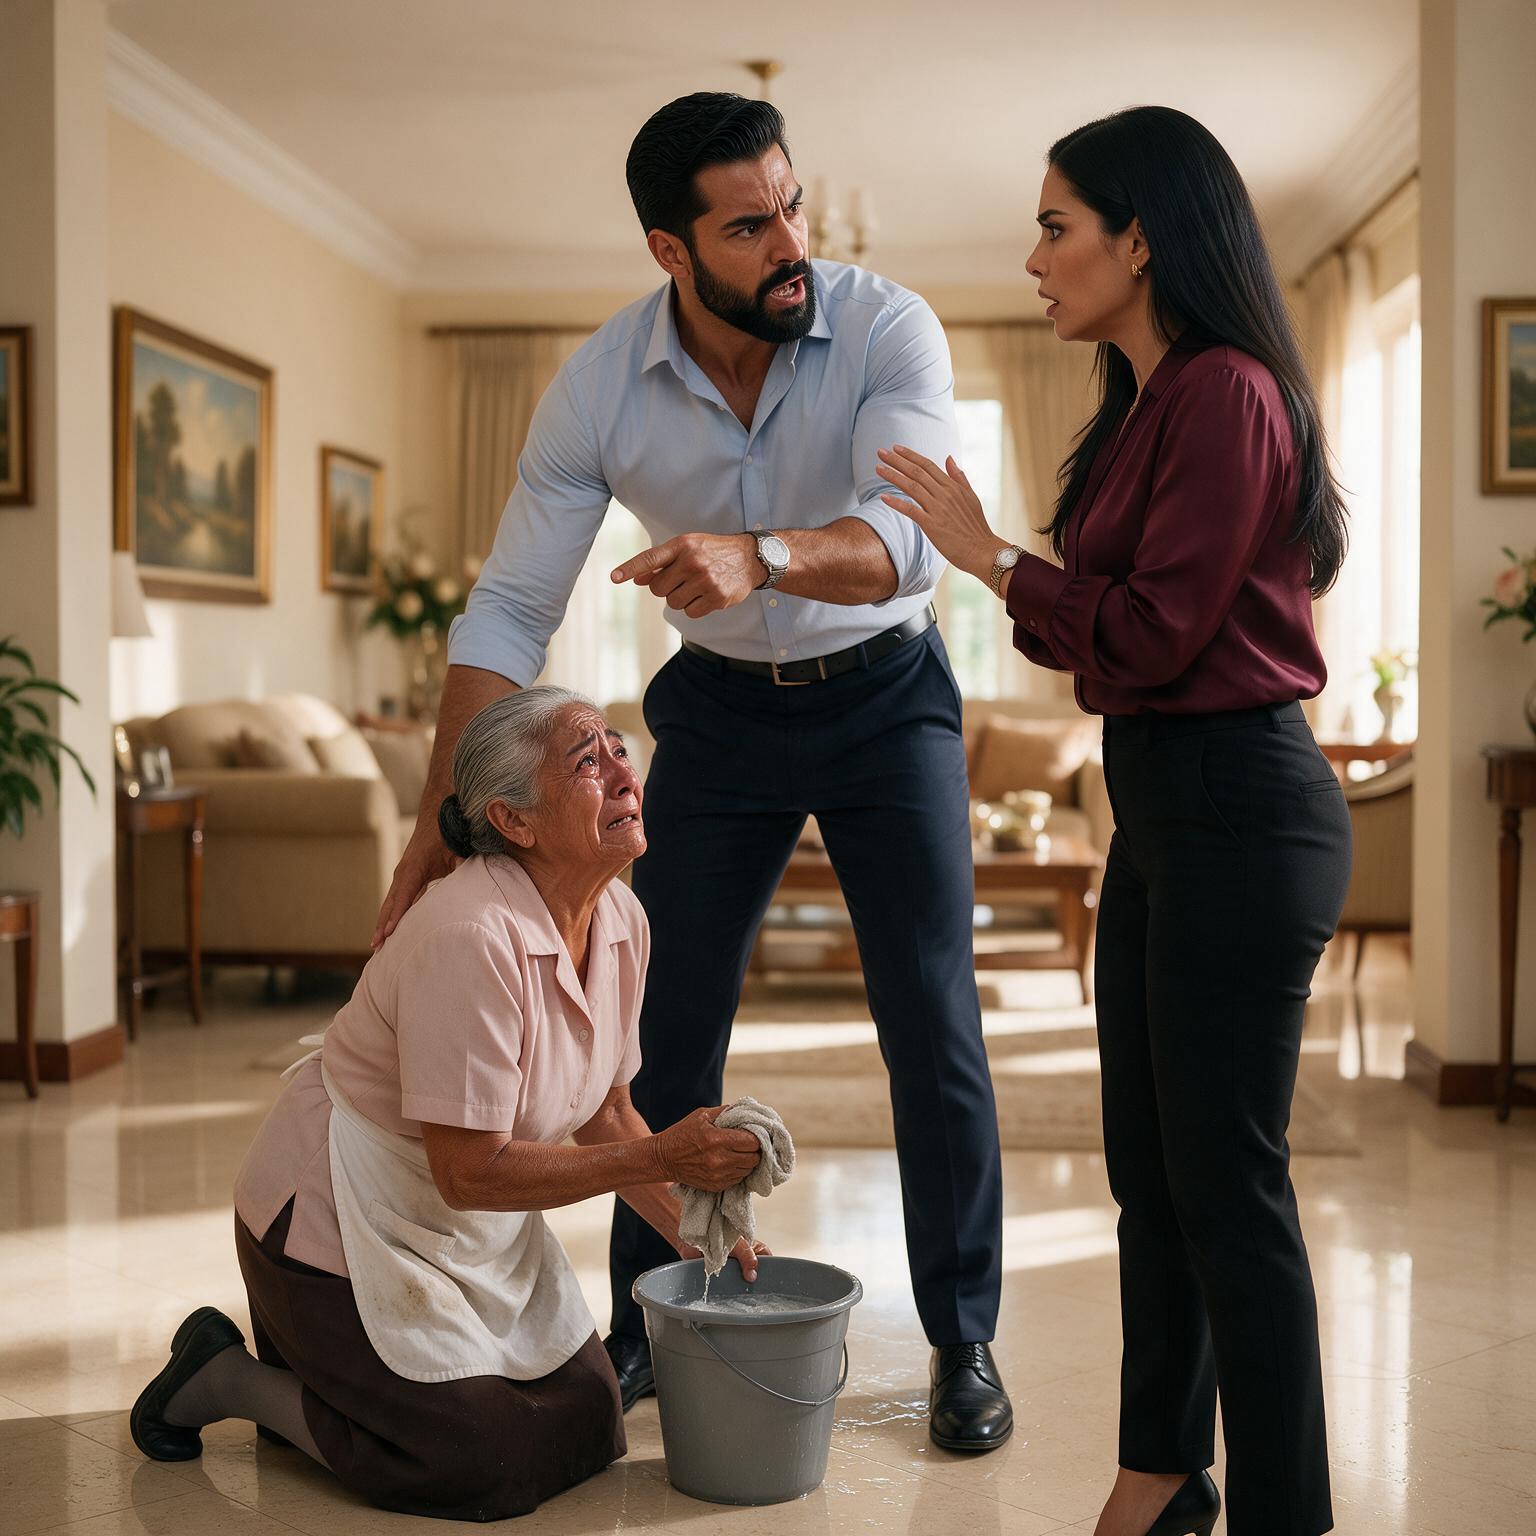
La voz de Álvaro resonó en el salón mientras Teresa pasaba lentamente un paño húmedo por el suelo. La anciana llevaba casi una hora arrodillada junto a un cubo de metal. Tenía las manos temblorosas y sentía un dolor punzante que subía desde las rodillas hasta la espalda.
A sus setenta y seis años, ya no poseía la fuerza de antes. Sin embargo, su hijo parecía incapaz de comprenderlo.
—Hijo, me duelen mucho las rodillas —murmuró.
Álvaro señaló una mancha cerca del sofá.
—Pues termina esa parte y después descansas. Tengo una reunión importante y no quiero encontrar la casa sucia cuando regrese.
Teresa levantó la mirada.
Durante años había intentado convencerse de que su hijo solo atravesaba una mala época. Primero perdió su empresa. Después llegó con dos maletas y le pidió quedarse unas semanas. Teresa le abrió las puertas sin imponer condiciones.
Las semanas se convirtieron en meses.
Más tarde, Álvaro llevó a vivir allí a Claudia, su esposa. Poco a poco comenzó a comportarse como propietario. Cambió algunos muebles, trasladó las fotografías de Teresa a un cajón y empezó a presentarse ante los vecinos como dueño de la vivienda.
Teresa permaneció en silencio porque temía perder al único hijo que le quedaba.
—Podrías contratar a alguien —dijo ella—. La pensión apenas me alcanza, pero intentaré pagar una parte.
Álvaro soltó una risa amarga.
—¿Contratar a alguien mientras tú vives aquí sin aportar nada?
La anciana lo miró, desconcertada.
—Esta es mi casa.
El rostro de Álvaro se endureció.
—No empieces otra vez con eso.
—Tu padre y yo la compramos hace cuarenta años.
—Papá quería dejármela. Lo sabes perfectamente.
—Pero nunca lo hizo.
Álvaro se inclinó sobre ella.
—Si sigues repitiendo esas tonterías, acabarás en una residencia. Allí nadie tendrá paciencia contigo.
Teresa bajó la mirada. Aquella amenaza siempre conseguía silenciarla.
En ese momento se escucharon unos pasos en el pasillo.
Claudia apareció en el salón con una carpeta bajo el brazo. Había regresado antes del trabajo y se quedó inmóvil al ver a Teresa arrodillada, el cubo junto a ella y a Álvaro señalándole el suelo.
—¿Qué está pasando aquí?
Álvaro cambió inmediatamente de expresión.
—Nada. Mi madre insistió en limpiar.
—Eso no es verdad —susurró Teresa.
Claudia dejó la carpeta sobre la mesa.
—¿Por qué obligas a tu madre a limpiar de rodillas?
—No la estoy obligando. Vive aquí, come aquí y no paga nada. Tiene que ganárselo.
Teresa cerró los ojos. Escuchar aquellas palabras delante de otra persona multiplicaba su vergüenza.
Claudia se acercó, ayudó a la anciana a levantarse y la acompañó hasta el sofá.
—No vuelva a arrodillarse —le pidió.
Álvaro cruzó los brazos.
—No te metas en algo que no entiendes.
—Lo entiendo mejor de lo que imaginas.
—Es mi madre y esta es mi casa.
Claudia abrió la carpeta.
—Entonces, ¿por qué la casa está a su nombre?
El silencio fue absoluto.
Álvaro miró primero a su esposa y después a Teresa. Por primera vez, la anciana vio miedo en sus ojos.
—¿De qué estás hablando?
—Esta mañana fui al Registro de la Propiedad. Teresa Vega figura como única propietaria. No existe ninguna herencia a tu favor ni ningún documento que te conceda derechos sobre la vivienda.
—Mi padre pagó esta casa.
—La escritura demuestra que tus padres la compraron juntos. Cuando él murió, su parte pasó legalmente a Teresa.
Álvaro golpeó la mesa con la palma.
—¿Por qué has investigado a mi familia?
—Porque ayer recibí una llamada de una inmobiliaria preguntando si estaba de acuerdo con vender nuestra casa.
Teresa se incorporó sobresaltada.
—¿Venderla?
Álvaro miró hacia el maletín de cuero que había dejado junto al sofá.
Claudia siguió su mirada.
—¿Qué hay dentro de ese maletín?
—Documentos de mi empresa.
—Ábrelo.
—No tienes derecho a exigirme nada.
Claudia se acercó al maletín, pero Álvaro se interpuso.
—He dicho que no lo toques.
La violencia de su reacción confirmó sus sospechas.
Teresa comenzó a llorar.
—Álvaro, dime que no intentabas vender mi casa.
—Solo necesitaba conseguir liquidez. Iba a comprar otra vivienda para todos.
—¿Con qué autorización?
—Soy tu único hijo. Algún día todo esto será mío.
La anciana lo contempló como si acabara de descubrir a un desconocido.
—¿Estás esperando que muera?
Álvaro no respondió.
Claudia tomó el maletín antes de que él pudiera impedirlo. Estaba cerrado con una combinación, pero Teresa recordó que su hijo utilizaba siempre la fecha de nacimiento de su padre.
Marcó los seis números.
El cierre se abrió.
En el interior encontraron un contrato de compraventa, extractos bancarios y una copia de un poder notarial. La supuesta firma de Teresa aparecía al final de varias páginas.
Ella tomó uno de los documentos.
—Yo nunca firmé esto.
Claudia revisó los extractos.
—Se han transferido más de noventa mil euros desde su cuenta a la empresa de Álvaro.
—Ese dinero era para mi tratamiento —dijo Teresa—. Tu padre lo ahorró antes de morir.
Álvaro intentó arrebatarle los papeles.
—Puedo explicarlo.
—Explícalo delante de un abogado —respondió Claudia.
El timbre de la casa sonó en ese instante.
Álvaro se quedó completamente pálido.
Claudia miró a Teresa.
—Esta mañana, después de descubrir quién era la verdadera propietaria, llamé a alguien.
Abrió la puerta.
Un hombre con traje gris esperaba al otro lado. Llevaba una carpeta negra y una identificación profesional en la mano.
—Doña Teresa —dijo—, soy Julián Robles. He venido porque creemos que su hijo no solo intentó vender su casa.
El abogado miró a Álvaro.
—También pudo utilizar su identidad para solicitar varios préstamos.
PARTE 2: LOS DOCUMENTOS DEL MALETÍN
Julián extendió los documentos sobre la mesa. Teresa permanecía sentada en el sofá, sujetando el paño con el que había limpiado el suelo. Claudia se sentó a su lado, mientras Álvaro caminaba nerviosamente por el salón.
—El poder notarial fue firmado hace dos años —explicó el abogado—, durante la hospitalización de doña Teresa.
La anciana recordó aquel día. Había sufrido una neumonía y apenas podía mantenerse despierta. Álvaro le llevó varios papeles asegurando que eran necesarios para pagar el hospital y gestionar la medicación.
Ella confió en él.
—No sabía lo que estaba firmando —dijo.
—El poder le permitía administrar sus cuentas —continuó Julián—, pero no apropiarse del dinero ni vender la vivienda para beneficio personal.
Álvaro señaló los extractos.
—Todo fue para mantener la casa y pagar los gastos.
—¿Noventa mil euros? —preguntó Claudia—. ¿Cuánto cuesta ese reloj que llevas? ¿Y el coche nuevo que dijiste que había pagado tu empresa?
Álvaro guardó silencio.
El abogado mostró otro documento.
—Encontramos tres préstamos solicitados utilizando los ingresos y la propiedad de su madre como garantía. Si la operación de venta hubiera continuado, doña Teresa habría perdido la casa y todavía conservaría una deuda considerable.
La anciana se llevó una mano al pecho.
—Querías dejarme en la calle.
—¡No! —exclamó Álvaro—. Pensaba recuperar el dinero antes de que nadie lo descubriera.
—Eso no cambia lo que hiciste —respondió Claudia.
Él se volvió hacia su madre.
—Necesitaba salvar mi empresa. Si cerraba, lo perdía todo.
Teresa levantó la vista.
—Cuando perdiste tu negocio, te abrí mi casa. Cuando no podías pagar tus deudas, compartí contigo mi pensión. Cuando tu esposa llegó, le cedí la habitación más grande. ¿Qué más necesitabas quitarme?
—No fue así.
—Me obligaste a limpiar de rodillas en la casa que compré trabajando durante cuarenta años.
Álvaro bajó la cabeza, pero aún intentó justificarse.
—Tú nunca entendiste la presión que tenía.
—Y tú nunca entendiste mi miedo —contestó Teresa—. Cada día pensaba que, si me enfrentaba a ti, me abandonarías. Por eso soporté tus órdenes y tus amenazas. Preferí vivir como una criada antes que aceptar que mi propio hijo había dejado de quererme.
Aquellas palabras destruyeron las últimas defensas de Álvaro.
Claudia se quitó lentamente el anillo de casada y lo dejó sobre la mesa.
—¿Qué haces? —preguntó él.
—No puedo continuar al lado de un hombre que utiliza a su madre y falsifica documentos.
—Tú también viviste aquí.
—Porque me dijiste que la casa era tuya. Pensaba que Teresa se empeñaba en ayudar con la limpieza. Nunca imaginé que la amenazabas cuando yo no estaba.
Claudia tomó su bolso.
—No espero que ella me perdone por no haberlo visto antes, pero no participaré un día más en esta mentira.
Álvaro se acercó a Teresa.
—Mamá, no permitas que denuncien. Puedo devolverte el dinero.
—¿Cómo?
—Venderé el coche. Cerraré la empresa. Trabajaré en lo que sea necesario.
—¿Y mi firma?
—Cometí un error.
Teresa negó lentamente.
—Un error es olvidar una fecha. Tú planeaste cada documento mientras me llamabas inútil dentro de mi propia casa.
Julián explicó que el poder quedaría revocado aquella misma tarde. También bloquearían las operaciones pendientes y denunciarían las firmas falsificadas. Álvaro tendría cuarenta y ocho horas para abandonar la vivienda.
—Soy tu hijo —dijo él desesperadamente.
—Precisamente por eso duele tanto.
Dos días después, Álvaro salió con tres maletas. Antes de cruzar la puerta miró el salón, el cubo de metal y a Teresa sentada junto a la ventana.
Esperó que ella lo detuviera.
No lo hizo.
Durante los meses siguientes, Teresa recuperó parte del dinero. El coche y varios bienes de Álvaro fueron vendidos para cubrir las deudas. La investigación demostró que había utilizado los ahorros de su madre para sostener una empresa que llevaba años quebrada.
Claudia solicitó el divorcio, pero continuó visitando a Teresa. No buscaba una herencia ni un lugar donde vivir. La acompañaba al médico, la ayudaba con los trámites y, sobre todo, se sentaba a escucharla.
Casi un año después, Álvaro regresó.
Ya no llevaba reloj caro ni ropa elegante. Trabajaba como empleado en un almacén y entregaba cada mes una parte de su salario para devolver lo robado.
Encontró a Teresa regando las plantas del salón.
—No he venido a pedirte que retires la denuncia —dijo—. Solo quería decirte que ahora comprendo algo.
Teresa esperó.
—Yo creía que esta casa me pertenecía porque algún día la heredaría. Pero fui yo quien dejó de merecer entrar en ella.
Su madre no lo abrazó.
Tampoco lo perdonó de inmediato.
Señaló una silla frente a ella.
—Puedes sentarte diez minutos.
Álvaro obedeció.
Por primera vez en muchos años, no dio ninguna orden.
Junto a la puerta seguía el viejo cubo de metal, limpio y vacío. Teresa había decidido conservarlo como recordatorio, no de la humillación que sufrió, sino del momento en que dejó de tener miedo.
Álvaro pensó que lo peor sería perder la casa, el dinero y su matrimonio.
Pero su verdadero castigo fue comprender que aquella anciana arrodillada había sido la única persona que lo amó sin pedir nada a cambio.
Y él casi la dejó sin hogar dentro de la casa que siempre había sido de ella.